A one-person website can still face a business-sized claim. For solo publishers, affiliate business insurance should match your actual risks, rather than a checklist designed for every small business.
There are also two separate decisions: protecting your own business and earning commissions by referring readers to insurance providers. Buying coverage doesn’t enroll you in an affiliate program, and joining a program doesn’t insure your website.
Start with your exposure, then compare referral programs by approved payouts, audience fit, and tracking rules.
Key Takeaways
- Choose small business insurance around your publishing activities, client work, data collection, equipment, and contracts.
- Programs from Thimble, Simply Business US, Embroker, and Hiscox have different payable actions.
- A long cookie window or large commission doesn’t guarantee referral credit or reliable earnings.
Choose Affiliate Business Insurance Around Your Risks
A blog that publishes product reviews has different exposures from a business that also sells marketing advice. Collecting newsletter subscribers, hosting events, or working with clients changes the picture again.
Your activities, revenue, contracts, and location all affect coverage decisions. The U.S. Chamber’s guide to insurance for small businesses explains how business risks and legal requirements shape policy selection.
A sponsor or client may require particular coverage, even when a law doesn’t. Workers compensation may become relevant if you hire staff, depending on your location and business circumstances. Working at home doesn’t automatically make business equipment or liability part of your personal insurance.
This is general information, not individualized insurance advice. A licensed insurance professional can assess your business description, exclusions, and contractual obligations.
Liability Insurance for Publishing and Client Work
General liability addresses physical and certain advertising claims
General liability commonly addresses third-party bodily injury and property damage. Some policies also include personal and advertising injury coverage, subject to their definitions and exclusions.
For a remote publisher without visitors, physical exposure may be limited. However, meetings, trade shows, and rented workspace can increase it.
New York’s Department of Financial Services explains the role of small-business liability coverage when negligence causes injury or property damage. Online publishers should also understand how their policy treats advertising-related allegations.
Professional liability addresses mistakes in services
Professional liability, often called errors and omissions insurance, addresses covered allegations that professional mistakes caused a client financial harm.
This may matter more if you sell SEO consulting, manage affiliate campaigns, or provide paid marketing advice. Pure publishing can require a different assessment, including whether media liability coverage fits your content risks.
Covered activities and exclusions matter more than the policy name. A consulting policy may not cover every allegation involving published reviews, intellectual property, or misleading statements. Neither policy guarantees protection against every dispute arising from your website.
Cyber and Property Coverage for a Home Office
Cyber insurance addresses covered digital incidents
Subscriber databases, contact forms, administrator accounts, and third-party plugins create digital exposure. Cyber coverage may address incident response, data recovery, liability, and certain interruption losses, depending on the policy.
The FTC’s cyber insurance guidance distinguishes protection for your own losses from claims involving others.
However, ordinary ranking declines, broken affiliate links, or a merchant cutting commissions aren’t automatically insured losses. Coverage depends on the triggering event and policy wording.
Use our affiliate website security checklist alongside insurance. Strong passwords, updates, and tested backups reduce preventable problems.
Business property insurance protects covered equipment
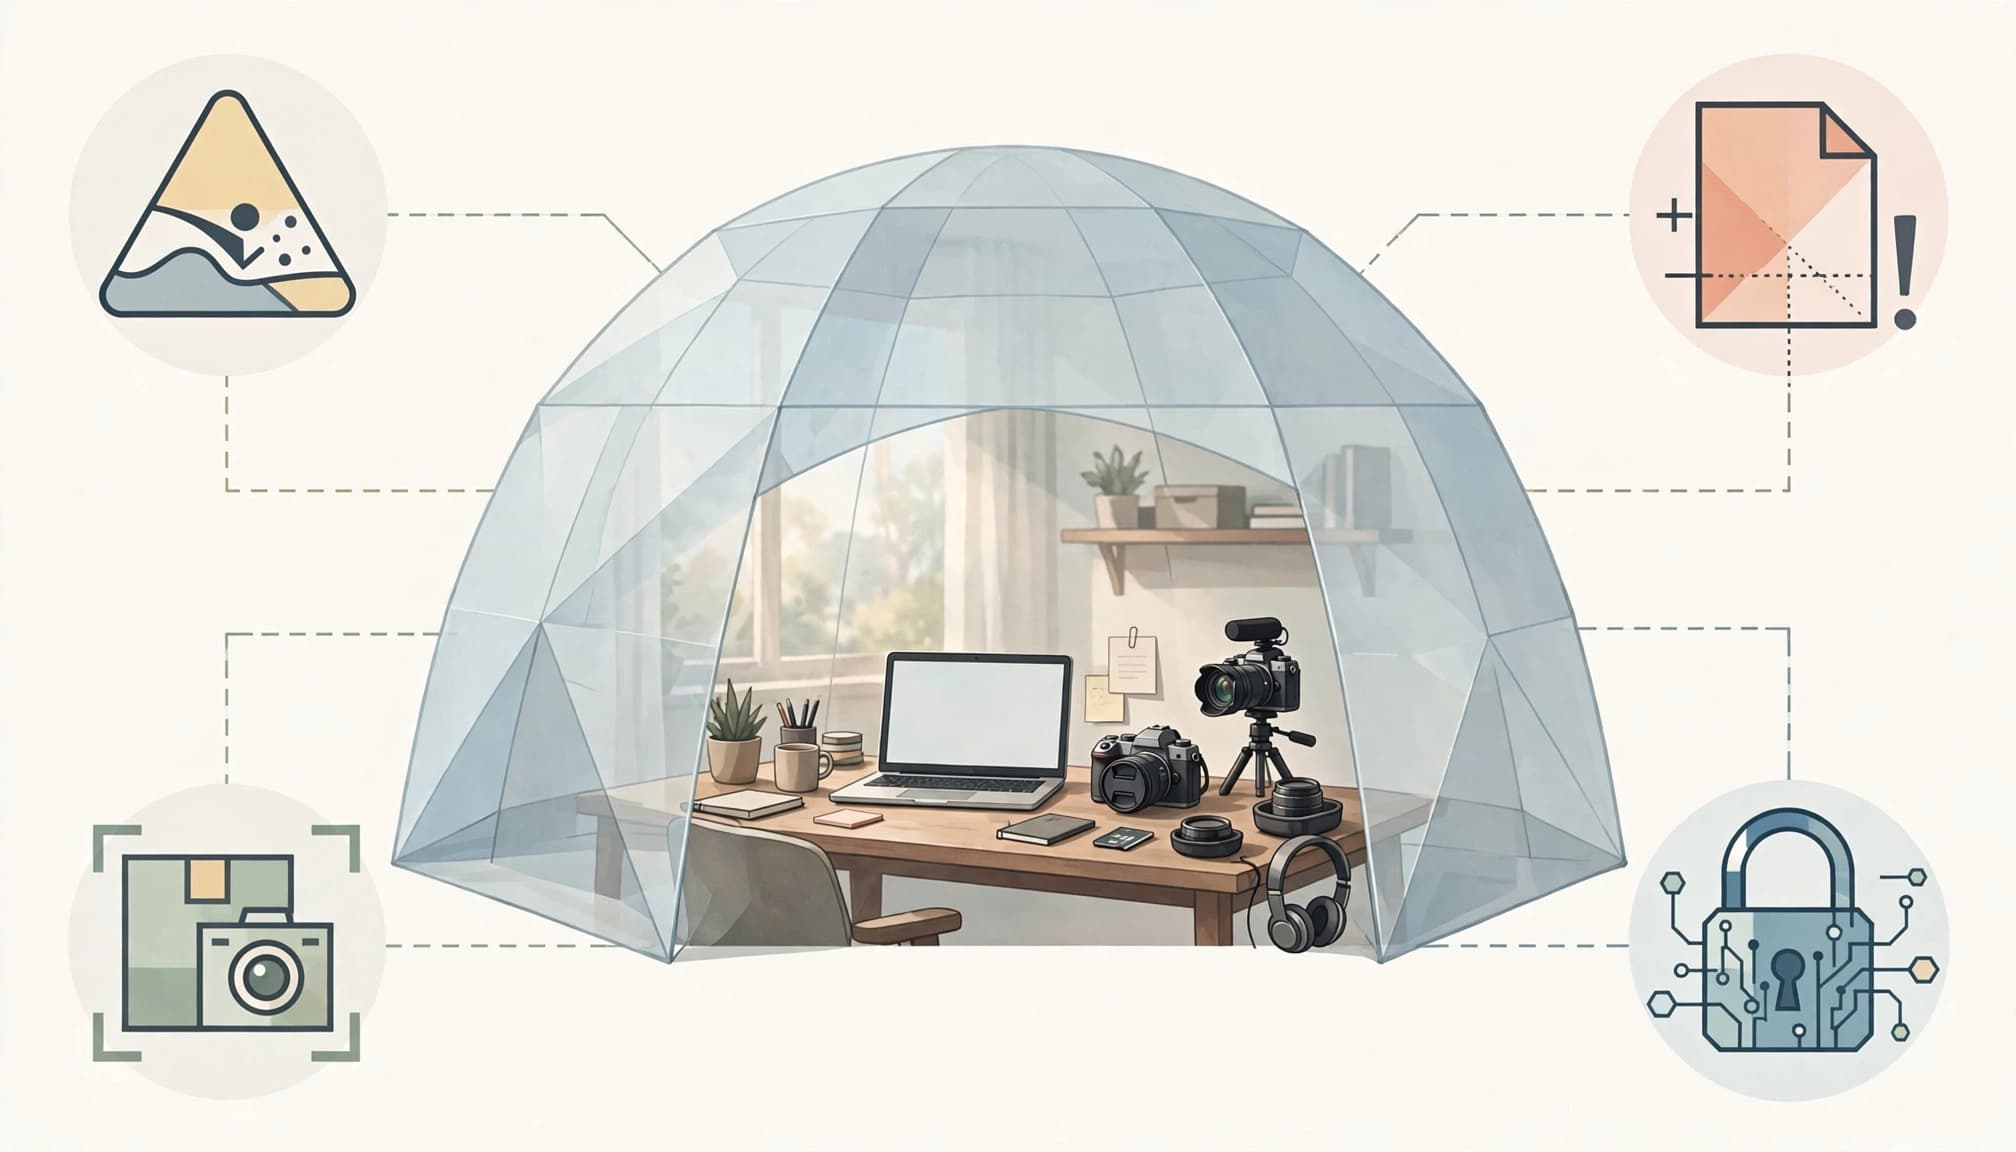
Commercial property or suitable home-business coverage may protect equipment against covered losses. Relevant assets include computers, cameras, and other equipment used to produce content.
Replacement value, deductibles, off-premises use, and covered causes of loss affect usefulness. A publisher with inexpensive equipment may make a different decision from someone running a video studio.
Physical equipment coverage also doesn’t automatically replace lost commissions during an outage. Business interruption coverage has its own conditions.
Compare Insurance Affiliate Offers
An insurance affiliate program pays publishers for an eligible referral action. The publisher introduces prospective customers, and the insurer or insurance agency handles quotes and policies.
These programs use different commission rates and payment structures. A per lead payment depends on the program’s eligibility criteria, so it isn’t equivalent to payment for a completed quote or company signup. The tracking window shows the cookie duration when public terms provide it.
| Program | Payment basis | Tracking window |
|---|---|---|
| Thimble | Default $30 per qualified lead | Not stated in the available public terms |
| Simply Business US | $50 per lead on FlexOffers | 30 days |
| Embroker | Average $250 per company signup | 30 days |
| Hiscox | $25 per completed quote | Not stated on its official affiliate page |
These payouts aren’t equivalent. A completed quote, qualified lead, and company signup can require different effort from the reader.
Thimble serves over 300 kinds of small businesses, while Embroker targets businesses including startups and solopreneurs. Founded in San Francisco in 2015, Embroker offers cyber and commercial crime insurance.
CoverWallet offers general liability, workers compensation, commercial property, professional liability, cyber liability, and other business lines. That range can suit content for readers comparing several coverage needs.
ERGO NEXT is another insurance affiliate option. Its insurance pages state that coverage is subject to underwriting and isn’t available in every state. Discounts vary by state. Hiscox and NEXT premium figures shown before an official quote are estimates, not guaranteed prices.
How Applications and Affiliate Payments Work
Thimble provides a defined application and payout schedule
Thimble runs its insurance affiliate program through Impact Radius. Applications are usually processed within 10 business days, and the program is US only.
Thimble pays $30 per lead when the referral qualifies, although audience and performance can affect the commission rate. There’s no monthly earnings cap.
Approved transactions are paid 20 days after the end of the month in which the click converted. That schedule separates the conversion date from cash arrival, so pending commissions shouldn’t fund immediate expenses.
Thimble also states that affiliates don’t need to be licensed insurance agents. That permission applies to participation in its referral program, not individualized insurance advice.
Other programs have separate approval processes
Each affiliate program has a separate approval process. Simply Business US accepts applications through FlexOffers, where its compliance team must approve participation. The listing provides a 30-day cookie and $50 per lead.
Embroker’s official affiliate page describes 30-day tracking through ShareASale and monthly payments on net-30 terms. Its stated average $250 payment per company signup isn’t guaranteed for every referral.
Hiscox uses CJ Affiliate and says it reviews applications within three business days. Its official payment description is $25 for a completed quote, not $25 per lead.
For onboarding, provide accurate website and traffic information, complete tax and payment details, and use approved tracking links. Reconcile Thimble’s Impact Radius network report with your own click and payment records. Publish clear commission disclosures near recommendations, and avoid implying firsthand experience you don’t have.
Consumer Insurance Offers Need a Different Audience
A consumer offer may fit publishers whose readers are comparing life insurance, auto insurance, or travel insurance. Attractive payouts alone don’t establish audience fit.
The following are published roundup figures, rather than confirmed current program offers.
| Program | Reported commission | Reported cookie |
|---|---|---|
| Health IQ | $150 per sale | 30 days |
| Allstate | $28 per lead | 5 days |
| Gerber Life | $25 per sale | 1 day |
| RoamRight | 15% per sale | 365 days |
Health IQ’s $150 per sale is the largest fixed payment in that comparison. However, that doesn’t make it the highest-earning option for business-focused traffic.
RoamRight’s 15% per sale can’t be compared directly with a flat lead payment without knowing the eligible purchase amount. Meanwhile, Gerber Life’s one-day window leaves much less time for a delayed conversion.
Choose an offer because it answers your readers’ needs. Life insurance, auto insurance, and travel insurance have different buying intentions from professional liability or cyber coverage. A large headline payment on an unsuitable offer can produce no approved commissions.
Cookies, Qualified Leads, and Reversals Affect Earnings
A cookie window sets a deadline, not guaranteed ownership
The cookie duration is generally 30 days, allowing an eligible conversion within that period. Attribution rules, not the duration alone, determine who receives credit.
Another affiliate click, a different device, blocked tracking, or deduplication rules can affect the result. Your analytics may record an outbound click without the network recording a payable conversion.
A 30-day cookie is a tracking window, not a promise that every later purchase belongs to your account.
Keep click dates, sub-IDs, credited conversions, and payment records together. Our weekly affiliate website workflow can help make reporting a regular habit.
Approved earnings matter more than headline rates
Cost-per-lead programs pay per lead only when the lead meets the program’s eligibility rules, not necessarily when a policy is sold. Qualification can involve geography, business type, valid contact information, and duplicate or fraud controls.
Cost per action pays for the defined action, such as a completed quote or signup. Revenue share pays a percentage of eligible revenue; recurring payments depend on continued eligibility.
Separate pending, approved, reversed, and paid commissions. Also record thresholds, payment dates, and reversal reasons. Net earnings after reversals and traffic costs provide a stronger comparison than the advertised commission alone.
Frequently Asked Questions
Do solo affiliate website owners need every policy?
No. Coverage needs depend on business activities, revenue, contracts, location, and the losses you can absorb. Client services, visitor contact, sensitive data, and expensive equipment each change the assessment.
Do insurance affiliates need an agent license?
Thimble explicitly says its affiliates don’t. However, selling, soliciting, or negotiating insurance can trigger state licensing requirements. Program membership doesn’t authorize you to provide individualized coverage recommendations.
Which business insurance program pays the most?
Among the official figures described here, Embroker states an average $250 per company signup. However, averages and signup payments aren’t directly comparable with fixed payments for leads or completed quotes. Business-focused signup figures also shouldn’t be compared directly with offers for life insurance, auto insurance, or travel insurance, which target different audiences. Audience fit and approval rates determine actual earnings.
Build Protection and Referral Income Separately
Choose coverage that matches your work, rather than buying every policy associated with a small business. Digital risks, client obligations, and equipment losses deserve separate consideration.
For referral income, compare the eligible action, attribution rules, and approved payment schedule when assessing an insurance affiliate program. Treating insurance protection and affiliate earnings as separate decisions keeps both tied to the business you actually run.